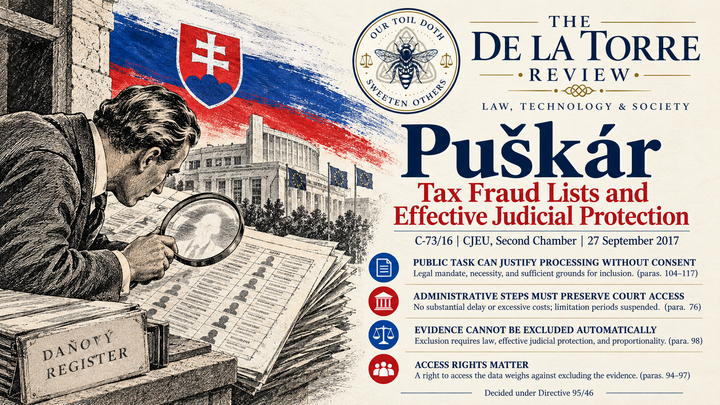
Puškár: Tax Fraud Lists, Court Access, and the Limits of Procedural Barriers
Tax authorities may process personal data without consent, but a public-interest purpose does not settle whether a particular person belongs on a suspected-fraud list. In Puškár, the CJEU also explained why administrative procedures and rules of evidence must preserve effective access to a court.